Batumi in 2027–2030: what happens when the new apartments are finished?
Up to 58,000 flats in the 2025–2029 construction pipeline, a rental market that may almost double, and the risk of competing with hundreds of lookalike studios. A buyer’s guide to the next cycle in Batumi.
Batumi in 2027–2030: what happens when the new apartments are finished?
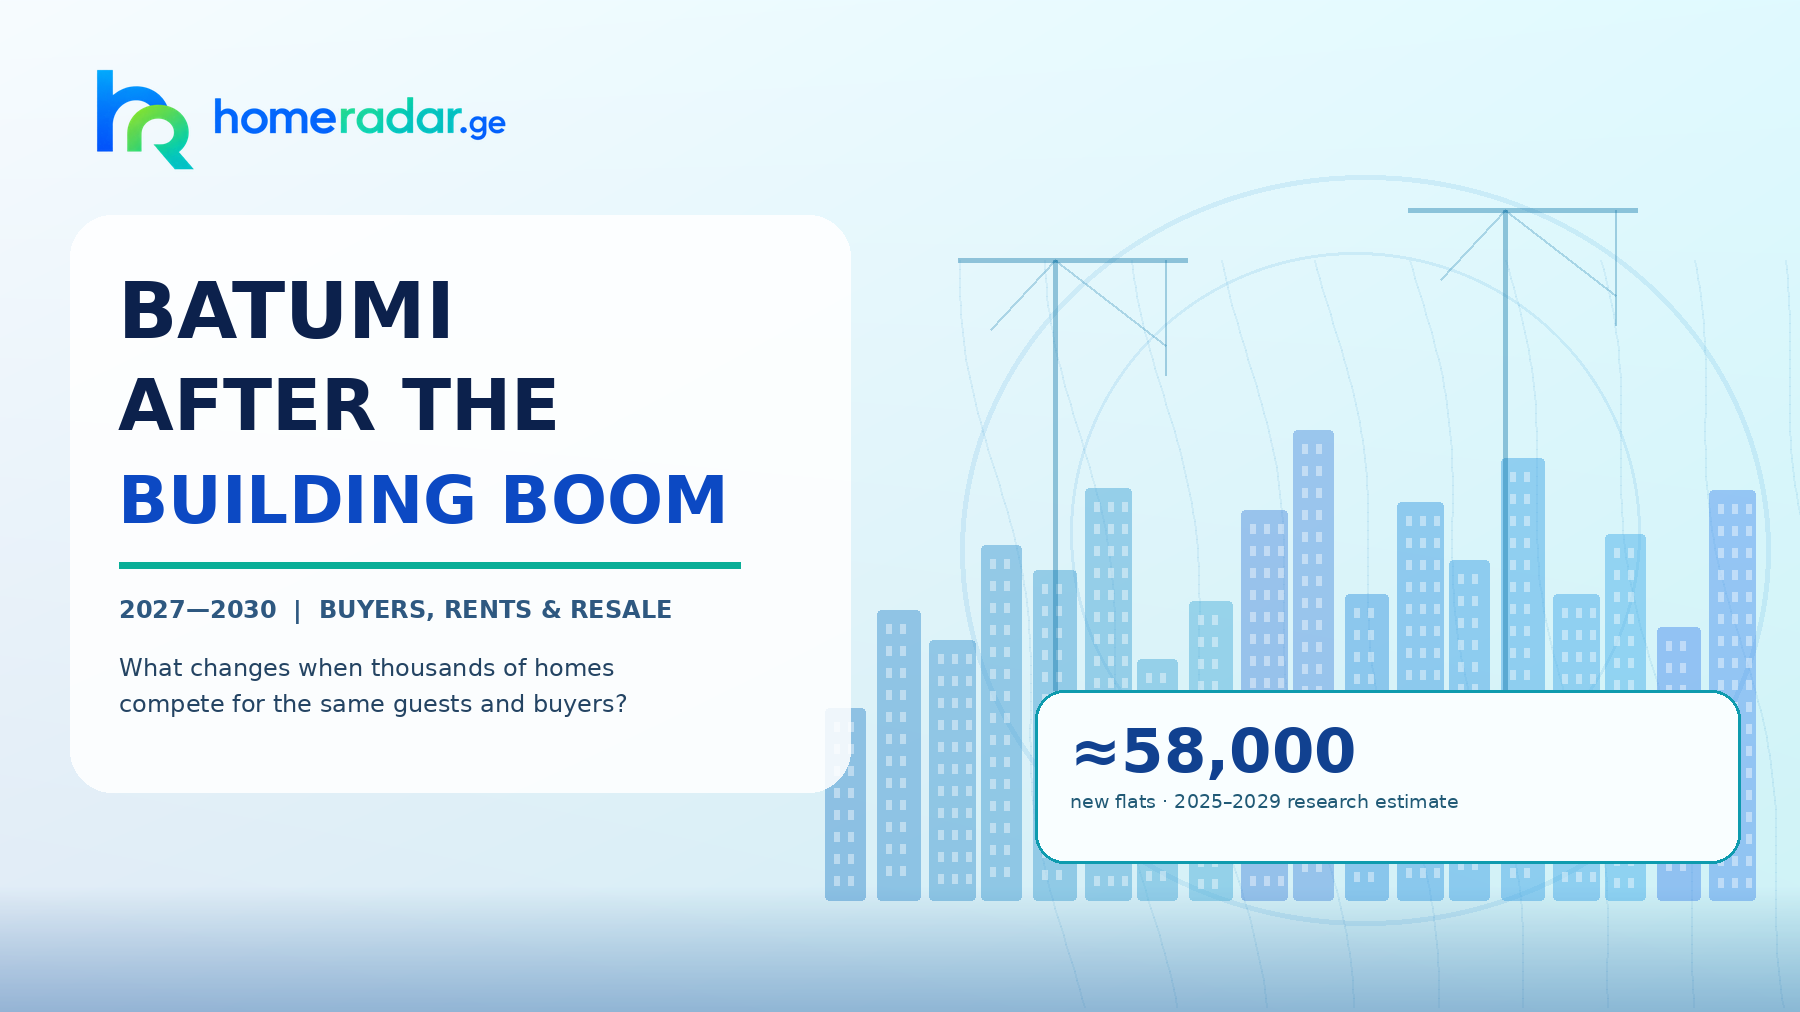
Batumi is not necessarily heading for a property-price crash. It is heading for a test of how many new apartments buyers and renters can absorb. Galt & Taggart estimated roughly 58,000 apartments in the 2025–2029 construction pipeline, around 46,300 of them intended for investment use. The central risk is not every new home losing value: it is a large number of similar rental units competing for the same guests.
That distinction matters now. The apartments delivered in 2027–2030 will arrive into different local markets: tourist studios near the waterfront, hotel-managed suites, family apartments and smaller low-rise residences. A buyer of a 30 m² studio is not taking the same risk as a family buying a well-planned flat to live in year-round.
A large pipeline, but no automatic collapse
The 58,000 estimate is a five-year pipeline for projects underway in the 2025 Galt & Taggart study. It is neither a count of unsold units nor a promise that all buildings will be handed over on schedule. The two components are approximately 46,300 investment flats and 11,400 homes for personal use; numbers are rounded.
Demand has not disappeared. Galt & Taggart recorded 17,478 registered apartment transactions in 2025, up 15% year on year, while warning that unsold developer stock continued to rise and returns were moderating. Colliers reported 1,614 registered deals in September 2026, down 10.4% from a year earlier, and a weighted average new-build transaction price of $1,408/m², up 5.2%. Bulk registrations in the prior year distort some comparisons, so transaction counts are not a live measure of reservations.
The useful forecast is therefore conditional: if tourism and permanent-resident demand do not keep pace with completions, landlords compete harder on price and service. If demand broadens and completed buildings deliver better amenities and transport, parts of the market can remain resilient. Neither outcome can be guaranteed citywide.
Galt & Taggart — pipeline · Galt & Taggart — 2026 outlook · Colliers — Sep 2026
2027–2030: which completions should buyers watch?
The examples below are project-level milestones, not a complete census of new flats. Developers may hand over shells and turnkey units in different periods; the contract for the exact block controls.
| Target | Project / evidence | What it means for 2027–2030 |
|---|---|---|
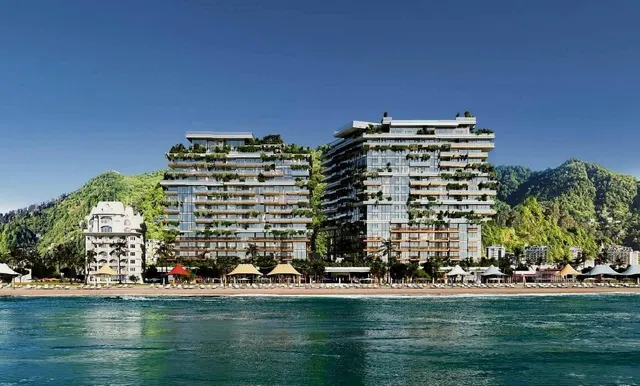
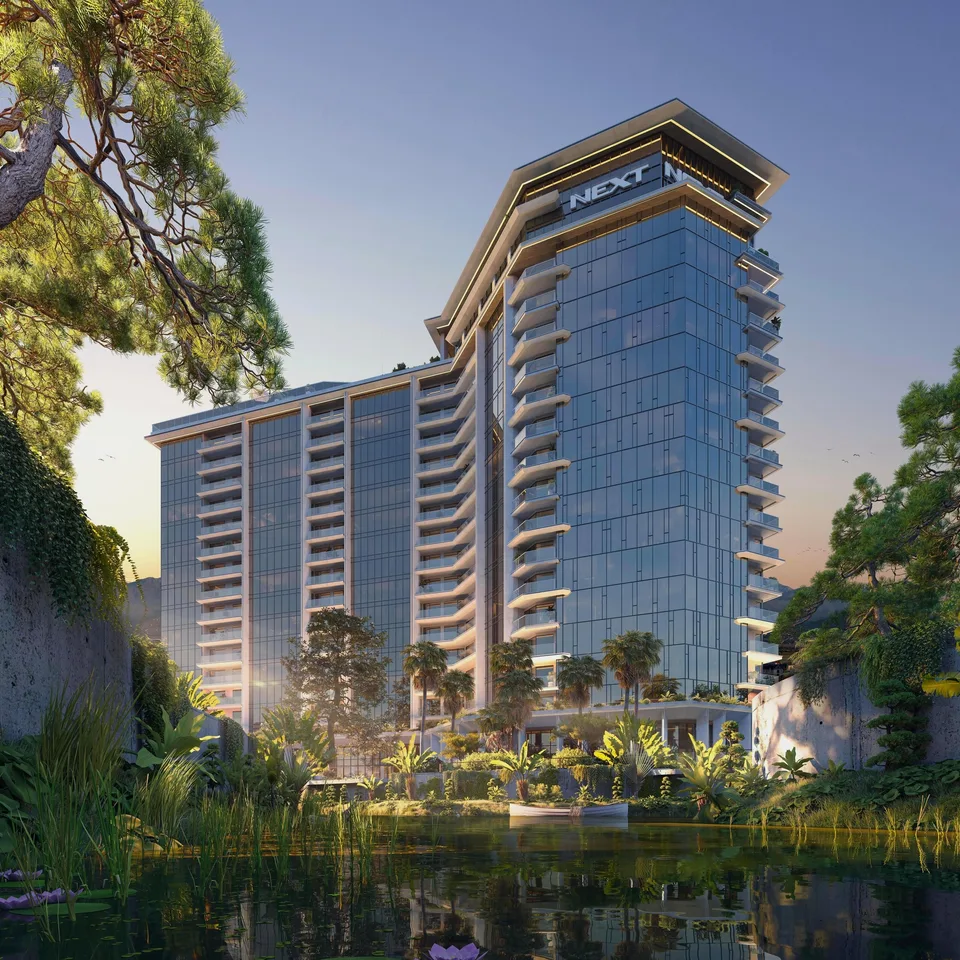
2027–28 | NEXT Gardens | White-frame handover planned for Dec 2027; turnkey option June 2028; Near-sea rental competition expands |
2028–29 | NEXT Magnolia | White-frame Dec 2028; turnkey April 2029 on developer timetable; Rental income starts after fit-out, not upon booking |
2028 | Montemar | HomeRadar project guide indicates delivery in 2028; Gonio adds managed hotel-style supply |
2029–30 | Strada | Public timeline references are inconsistent; confirm the block and handover date; A later delivery changes break-even economics |
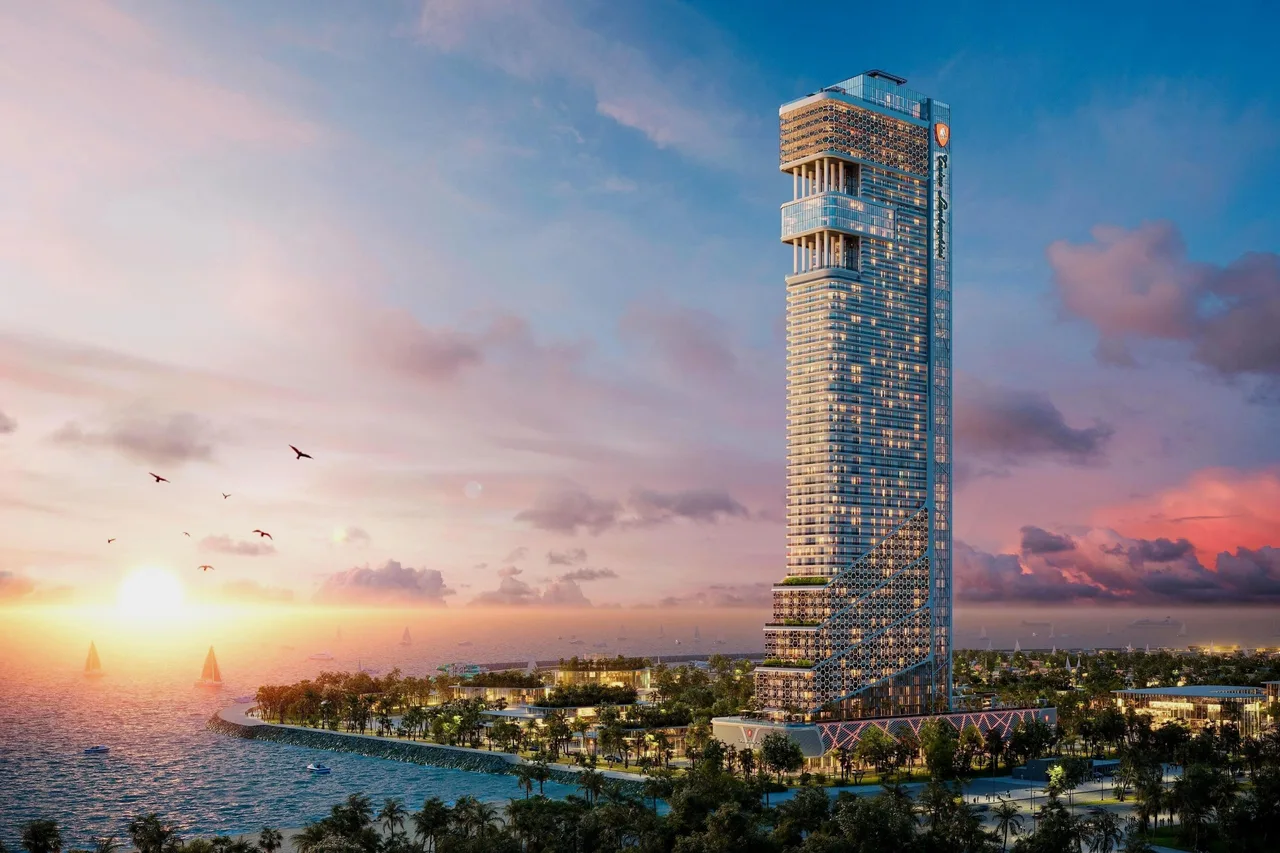
2030 | Lux Home / Tonino Lamborghini Tower | Lux developer states 2030; HomeRadar shows 2030 for the tower; Long wait, premium or differentiated supply |
2027–28
- Project / evidence
NEXT Gardens
- What it means for 2027–2030
White-frame handover planned for Dec 2027; turnkey option June 2028; Near-sea rental competition expands
2028–29
- Project / evidence
NEXT Magnolia
- What it means for 2027–2030
White-frame Dec 2028; turnkey April 2029 on developer timetable; Rental income starts after fit-out, not upon booking
2028
- Project / evidence
Montemar
- What it means for 2027–2030
HomeRadar project guide indicates delivery in 2028; Gonio adds managed hotel-style supply
2029–30
- Project / evidence
Strada
- What it means for 2027–2030
Public timeline references are inconsistent; confirm the block and handover date; A later delivery changes break-even economics
2030
- Project / evidence
Lux Home / Tonino Lamborghini Tower
- What it means for 2027–2030
Lux developer states 2030; HomeRadar shows 2030 for the tower; Long wait, premium or differentiated supply
NEXT — milestones · LUX Home — handover · Montemar — HomeRadar · Tonino Tower — HomeRadar
Where will the competition be strongest?
Galt & Taggart mapped more than 22,000 planned flats to the New Boulevard area and over 12,000 to Heroes Alley in the pipeline surveyed in October 2025. These are the report’s geographical definitions and cannot be directly translated into HomeRadar’s smaller neighbourhood categories. The concentration matters: renters can compare buildings within a short walk, and owners reselling into a large stock of similar homes face more competing listings.
The same pressure should not be applied mechanically to all of Gonio, Green Cape or inland residential Batumi. A quiet family building and an investment hotel can have different seasonality, operating charges and resale audiences. A truly useful comparison looks at apartments with the same size, delivery condition and immediate local competition.
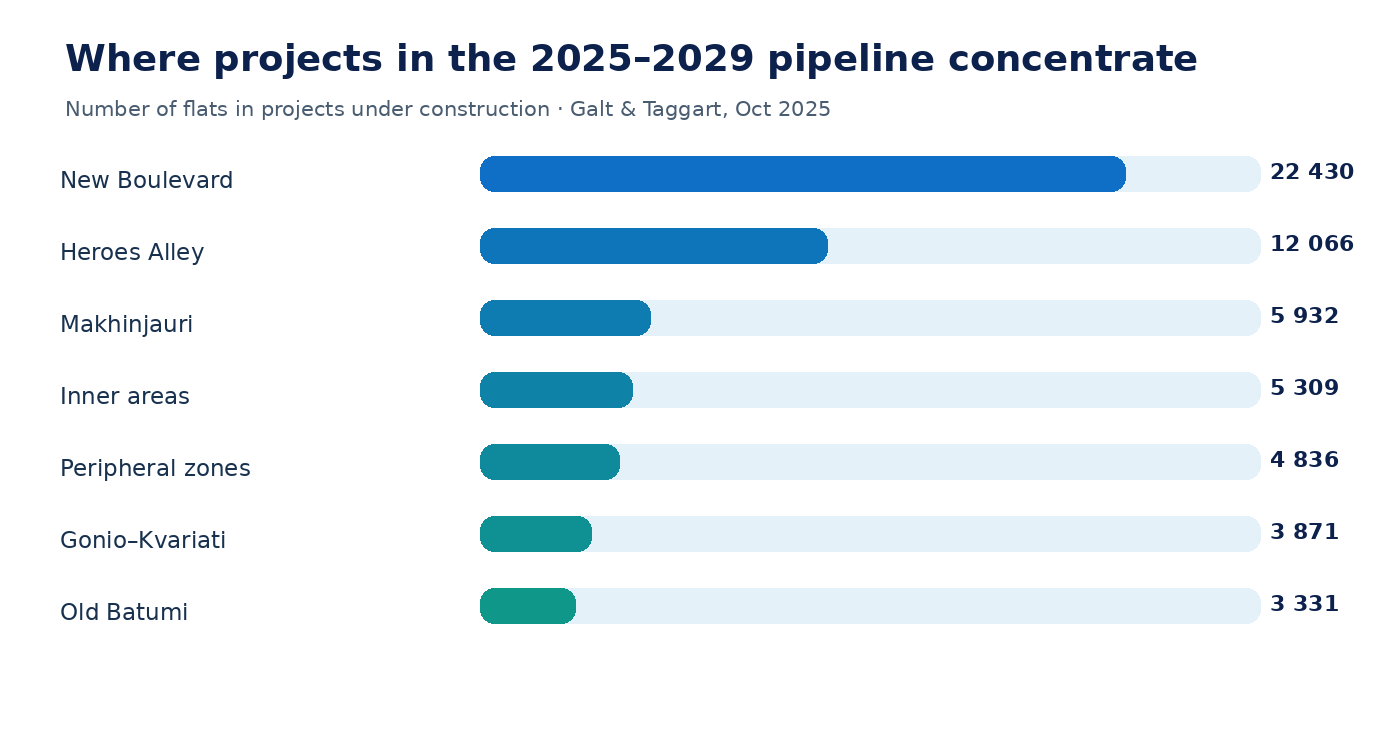
Pipeline distribution uses Galt & Taggart’s October 2025 district definitions, which differ from HomeRadar’s current microdistrict scheme.
What happens to holiday-rental returns?
In its 2025 research, Galt & Taggart projected that the pool of short-term-rental apartments could increase from about 18,000–20,000 at the end of 2024 to 35,000–40,000 at the end of 2029. Its scenario model linked annual tourist growth of 5%, 10% and 15% to average rental yields in 2029 of 3.4%, 5.1% and 7.4%, assuming average length of stay does not change. These are research scenarios, not a forecast of what any particular flat will earn.
To see the sensitivity in everyday terms, imagine an $85,000 all-in investment, a $55 nightly rate and 30% model operating costs. At 47% annual occupancy, net operating receipts before owner-specific taxes or capital reserves are about $6,605. If occupancy falls to 37% with the same nightly rate, they drop to about $5,199 — a $1,405 annual difference. Small changes in occupancy matter more to some investors than a glossy projected increase in resale price.
Galt & Taggart’s 2029 rental-yield scenarios
| Growth of tourist numbers | Average rental yield 2029 |
|---|---|
+5% | 3.4% |
+10% | 5.1% |
+15% | 7.4% |
+5%
- Average rental yield 2029
3.4%
+10%
- Average rental yield 2029
5.1%
+15%
- Average rental yield 2029
7.4%
Galt & Taggart scenario: 2029 yield conditional on annual tourist growth and constant average stay. Not a prediction for a specific project.
Two different markets: investment studios and homes for living
The investment segment carries the sharper short-stay exposure. The 2025 study found that more than half of the investment apartments being built were mid-market studio-type units. If many enter the rental market together, landlords will have to compete on maintenance, reviews, service, reliable Wi-Fi and realistic winter pricing, not simply a sea-view image.
Year-round residential housing has a different test: schools, noise, winter heating, parking, lifts, construction quality and the supply of genuinely comparable family units. New apartments may improve residents’ options without forcing every district’s prices lower. A larger flat may be less liquid because it has a higher ticket, but that cannot be inferred from citywide studio supply alone.
What would a buyer do differently today?
For a rental investment, look beyond the future developer launch. Identify completed or nearly completed direct competitors within walking distance. Compare the full ready-to-rent purchase budget, management contract, fees, nearby construction and two occupancy scenarios. If a project opens in 2030, projected rents from 2027–2029 are zero until the unit can actually operate.
For a home, favour daily-use fundamentals and inspect the project’s construction timetable building by building. A lower presale price is useful only if waiting, finish condition and risks fit the family’s plans. For resale, ask who will buy the property later: another investor seeking yield, a resident, or a hotel-suite buyer bound by an operator agreement.
Buyers comparing examples can review NEXT Magnolia and Montemar as future-supply cases, Lux Home as a 2030 case, and Guru Status as a completed point of reference. HomeRadar project cards are a dated starting point; written confirmation of the exact unit and legal status is still necessary.
NEXT Magnolia · Montemar · Lux Home · Guru Status
The likely winner is not “Batumi” but the right apartment
A broad market of new apartments may continue to expand, even as its weakest rental concepts suffer falling occupancy or need larger discounts. A distinctive, well-operated apartment can hold up better, but it is not exempt from market risk. The sensible 2027–2030 strategy is to price the competition first, buy the documented unit second, and leave guaranteed double-digit returns out of the calculation.
Frequently asked questions
Will 58,000 flats come onto the market in 2029?
No. The research describes a cumulative 2025–2029 pipeline, and handovers may slip or occur by block. It does not say that 58,000 units suddenly become available in one year.
Does that mean prices will fall?
Not automatically. More supply can limit price growth or force discounts in comparable projects, but location, finish, demand and building quality can create different outcomes.
What is most exposed to competition?
Similar small short-stay investment studios in clusters with many nearby completions are especially sensitive to occupancy and price competition.
Can annual tourist growth offset the extra apartments?
Possibly. Galt & Taggart modelled distinct 2029 yield outcomes for 5%, 10% and 15% annual tourist growth; these depend on an unchanged length of stay and other assumptions.
Will a building completed in 2030 earn rent before handover?
No. The future operating model can be estimated now, but cash rent begins only after legal and practical readiness for guests.
Is a family apartment less risky?
It has different risks, not no risks: everyday infrastructure, construction quality, heating and resale liquidity matter more than short-stay booking metrics.
What should I ask the developer?
Unit number and status, registered rights, binding delivery date, finish specification, service fees, management rights, penalties for delay and the exact all-in cost.
Sources checked: 21 October 2026. Developer milestones and individual prices require fresh confirmation.
Projects mentioned 7
| Actions | |||||
|---|---|---|---|---|---|
| Airport | Ready | 58,650 $ | 1,850 $ | ||
| Gonio-Kvariati | Planned | 98,010 $ | 2,590 $ | ||
| Khimshiashvili | Planned | 73,000 $ | 2,380 $ | ||
| Airport | Building | 44,460 $ | 1,440 $ | ||
| Ambassadori Island | Planned | 184,870 $ | 3,860 $ | ||
| Gonio-Kvariati | Planned | 59,280 $ | 1,900 $ | ||
| Airport | Planned | 41,470 $ | 1,300 $ |