0% instalments in Batumi new builds: where is the real saving?
Interest-free developer instalments can help manage cash flow, but a full-payment discount may make the total purchase price lower. We compare public developer terms and a like-for-like example.
0% instalments in Batumi new builds: where is the real saving?
Zero interest is not necessarily the lowest price
An interest-free instalment plan lets buyers put down a deposit and pay the rest directly to a developer without a stated interest rate. It can be more manageable than paying in full. But the useful question is what that particular apartment actually costs. If the developer offers a discount for full payment, the instalment total is effectively higher. If the home is unfinished, the buyer must also fund payments before they can occupy or rent it.
Public terms checked on 21 October 2026 show very different arrangements: 20% deposits, plans running to construction completion and programmes extending to December 2029. No general marketing page replaces a dated payment schedule for the selected unit.
Four developers, four ways to spread payments
| Project | Down payment | Term/model | What differs |
|---|---|---|---|
Reside SELECT | 20% | To 2029 completion | Monthly or quarterly |
Artex Parkline / Premier | 20% | To December 2029 | 0% in-house instalments |
BANA Development | 20% | 0%; schedule on request | Green frame; Dec 2027 handover |
LUX Group | On request | 0%; negotiated | Direct developer payments |
Reside SELECT
- Down payment
20%
- Term/model
To 2029 completion
- What differs
Monthly or quarterly
Artex Parkline / Premier
- Down payment
20%
- Term/model
To December 2029
- What differs
0% in-house instalments
BANA Development
- Down payment
20%
- Term/model
0%; schedule on request
- What differs
Green frame; Dec 2027 handover
LUX Group
- Down payment
On request
- Term/model
0%; negotiated
- What differs
Direct developer payments
Reside SELECT publicly offers a 20% down payment followed by monthly or quarterly payments until completion, scheduled for 2029. Artex advertises a 20% deposit and zero-interest payments until December 2029, with unit-level details to be agreed. BANA Development promotes a 20% deposit and 0% financing for green-frame homes with a planned December 2027 delivery. LUX Group says it offers direct, interest-free developer instalments, but does not publish a universal deposit or term for every unit.
The cheapest monthly instalment does not identify the best purchase. Project status, finishing, location, overall price and contractual handover date can outweigh the apparent monthly difference. Compare one coherent purchase budget, not scattered advertising figures.
A like-for-like experiment: $80,000 versus a full-payment discount
Imagine exactly the same apartment priced at $80,000 on a 32-month interest-free plan, but $76,000 if paid in full. The 5% cash discount is hypothetical; it is not a verified promotion from any developer in this article.
| Item | Full payment | 0% instalments |
|---|---|---|
Same apartment price | $76,000 | $80,000 |
At signing | $76,000 | $16,000 (20%) |
Remaining payments | None | 32 × $2,000 |
Total paid | $76,000 | $80,000 |
Difference | — | +$4,000 |
Same apartment price
- Full payment
$76,000
- 0% instalments
$80,000
At signing
- Full payment
$76,000
- 0% instalments
$16,000 (20%)
Remaining payments
- Full payment
None
- 0% instalments
32 × $2,000
Total paid
- Full payment
$76,000
- 0% instalments
$80,000
Difference
- Full payment
—
- 0% instalments
+$4,000
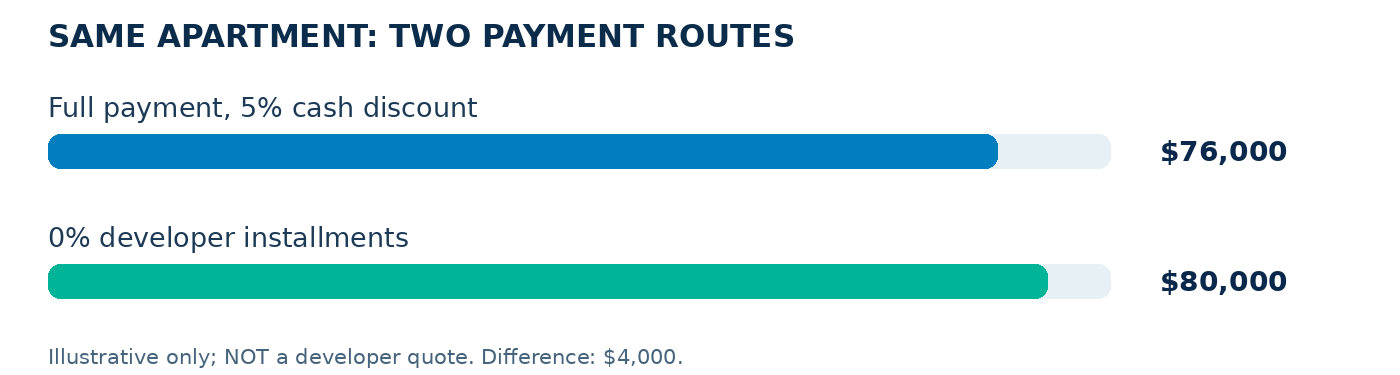
The instalment rate is still nominally 0%, yet the total paid is $4,000 more than with the hypothetical cash discount. That difference is 5% of the instalment price, or roughly 5.3% of the cash price. It is not a bank interest charge: it is the gap between two commercial offers. What the buyer receives in return is time to hold on to part of their cash.
Ask for two signed or dated quotations for the identical unit, covering the same floor, orientation, finish, handover date and included services. Then compare the complete cost and every payment date. A developer who cannot supply both terms leaves the question unanswered.
Four contract clauses that can change the decision
Price and currency
Is the full price fixed? Which currency governs the obligation, and what exchange rate applies on the payment date? A USD advertisement alongside GEL-denominated payments may create FX exposure. Do not assume a rate is locked unless the contract says so.
Payment timetable and default
Check whether instalments are equal, whether a balloon payment remains, what happens if a payment is late and whether the developer can terminate the agreement. A $2,000 monthly instalment calls for $6,000 to cover three payments if the buyer wants a simple short-term cushion.
Completion and legal rights
When will the unit actually be handed over, and in what condition? Does a construction delay alter the schedule? What rights are registered before final settlement? The Georgian Public Registry (NAPR) provides extracts about recorded ownership and restrictions; a lawyer should separately check the contract and the buyer’s route to registration.
Early settlement and resale
Ask whether prepayment reduces the price and whether rights can be assigned or the unit resold before the final instalment. Consent requirements and transfer charges can affect a buyer who needs to exit early.
Who benefits from a payment plan?
A future homeowner may prefer to preserve liquidity before handover, provided completion and fit-out timing suit the family. A rental investor must not count rent until the property is completed and operational; a small deposit is not the denominator for the return on a fully paid property. A cash-rich buyer should request a binding full-payment price before dismissing a discount. Buyers whose earnings fluctuate or sit in another currency should stress-test the monthly schedule first.
Where HomeRadar fits
Start with a specific apartment and a realistic all-in budget, then request two written payment options. HomeRadar provides separate investment and living comparisons, while participating developers may offer unit-specific terms to its audience. A partnership is not a promise of a discount and does not determine independent editorial assessment.
The practical verdict: 0% instalments are genuinely useful if the total price remains competitive, the timetable is affordable and the contractual protections are clear. The zero alone is insufficient evidence.
Frequently asked questions
Does 0% mean there is no extra cost?
Not necessarily. A lower cash price can create a price difference despite a zero nominal instalment rate. Compare the same unit on both terms.
Is 20% always the down payment?
No. Reside SELECT, Artex and BANA advertise 20% in the examples checked; it is not a market-wide rule.
Can I pay directly to the developer without a bank?
Yes, several developers describe direct interest-free plans. The contract determines payment obligations, buyer rights and the consequences of default.
Does an unfinished apartment produce rental income?
No. Rent can only start after handover, fitting out and actual operation.
Is the longest term always best?
No. Total price, cash-flow reliability, the handover date, currency and penalties matter more than the advertised duration.
Should I request a registry extract?
Yes. Verify registered property rights and restrictions, and obtain independent legal advice on the agreement and registration process.
Does HomeRadar guarantee special payment conditions?
No. Partner offers can vary by unit and date; all prices and instalment terms should be confirmed in writing.
Sources and verification date
Checked on 21 October 2026 against developer websites and the Georgian National Agency of Public Registry. Descriptions are indicative; only a dated quotation and signed agreement establish the selected apartment’s terms.
Reside SELECT • Artex • BANA • LUX Group
Projects mentioned 1
| Actions | |||||
|---|---|---|---|---|---|
| Chaobi | Building | 47,040 $ | 1,150 $ |